Current State of the Housing Market
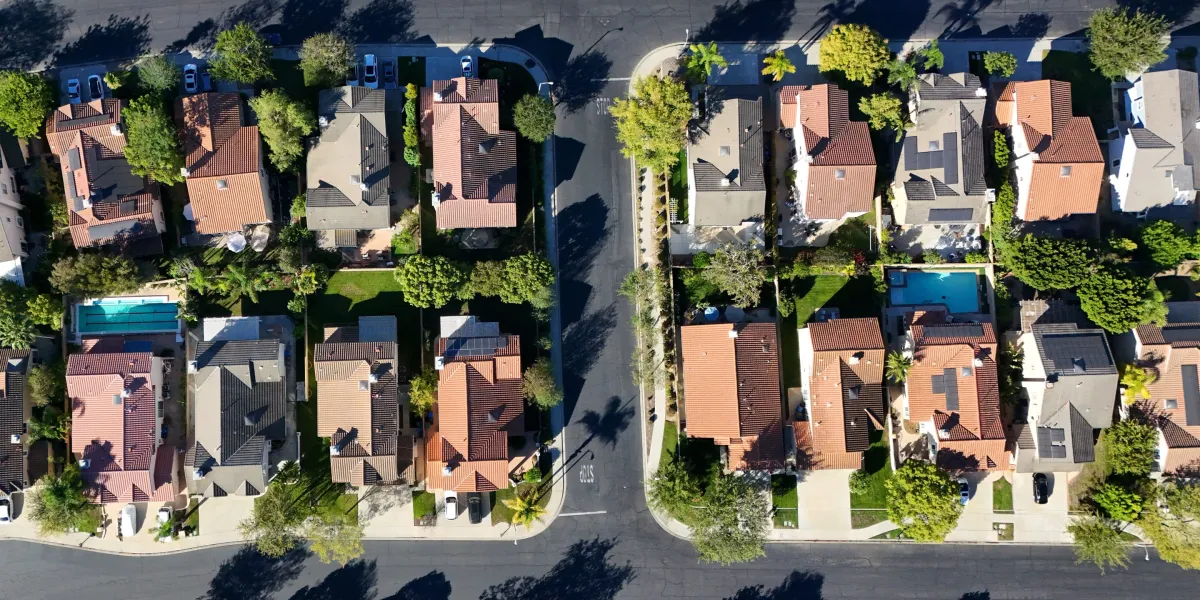
The U.S. housing market is facing significant headwinds as mortgage rates approach the 7% threshold, marking a critical juncture for buyers and sellers alike. This increase in borrowing costs has contributed to a notable decline in home sales, which have fallen to their lowest pace in over a year. As the financial landscape shifts, the impact on both prospective homeowners and current sellers is becoming increasingly evident.
Impact of Rising Mortgage Rates
Mortgage rates have steadily climbed in recent months, driven by inflationary pressures and a tightening monetary policy from the Federal Reserve. With rates now nearing 7%, many potential buyers are finding themselves priced out of the market. Higher monthly payments mean that affordability is rapidly diminishing, leading to a slowdown in demand. This trend is particularly alarming for first-time homebuyers, who often rely on favorable financing conditions to enter the market.
Decline in Home Sales
The consequences of rising mortgage rates are reflected in the latest sales figures, which indicate a significant downturn in transactions. Recent data reveals that home sales have dropped to their lowest levels since early last year, as buyers hesitate to commit to purchases amid escalating costs. This decline is not only a reflection of reduced buyer enthusiasm but also a sign of broader economic uncertainty that is affecting consumer confidence.
Sellers Respond with Concessions
In an effort to stimulate interest and attract buyers, sellers are increasingly offering concessions. These may include covering closing costs, making repairs, or even lowering the sale price. Such strategies are becoming commonplace as the market shifts from a seller's advantage to a more balanced or even buyer-favorable environment. While these concessions can help facilitate sales, they also indicate that sellers are feeling the pressure of a slowing market.
The Role of Economic Factors
Several economic factors are contributing to the current state of the housing market. Inflation remains a primary concern, leading to continued increases in interest rates as the Federal Reserve aims to stabilize prices. Additionally, rising costs of living and stagnant wage growth are further straining household budgets, leaving many consumers wary of making significant financial commitments such as home purchases.
Market Predictions and Future Outlook
Looking ahead, analysts are divided on the future trajectory of the housing market. Some predict that as inflationary pressures ease, mortgage rates may stabilize or even decline, potentially reigniting buyer interest. Others caution that the current economic climate could prolong the slowdown, leading to further declines in home sales and continued challenges for sellers. The uncertainty surrounding economic conditions makes it difficult to predict precisely how the market will respond in the coming months.
Impact on Home Prices
As sales slow and concessions become more common, questions arise regarding the potential impact on home prices. In a market characterized by declining demand, prices may be pressured to decrease, particularly in areas where inventory levels remain elevated. However, in certain regions with strong job growth and limited housing supply, prices may remain resilient despite broader market trends. The divergence in regional performance underscores the complexity of the current housing landscape.
Investor Sentiment and Market Dynamics
Investor sentiment is also shifting in response to the evolving housing market conditions. Many institutional investors, who previously capitalized on low mortgage rates and rising home values, are reassessing their strategies. Some are opting to hold off on new acquisitions, while others are exploring alternative investment opportunities in sectors less affected by rising interest rates. This shift in investor behavior may have longer-term implications for the housing market and its recovery.
Challenges for First-Time Homebuyers
First-time homebuyers are facing significant challenges as they navigate the current housing market. With rising mortgage rates and elevated home prices, many are finding it increasingly difficult to secure financing and afford their first home. Programs aimed at assisting first-time buyers, such as down payment assistance and favorable loan terms, are being scrutinized as demand wanes. The need for innovative solutions to address these challenges has never been more pressing.
The Long-Term Implications of Market Adjustments
The adjustments occurring in the housing market may have long-term implications for both buyers and sellers. For buyers, the current slowdown could represent an opportunity to enter the market at a more favorable price point, provided they can navigate the challenges of higher mortgage rates. For sellers, the need to adapt to a more competitive landscape may require a reevaluation of pricing strategies and marketing efforts. Over time, these shifts could lead to a more balanced market that better serves the needs of all participants.
Conclusion: Navigating Uncertainty
The housing market is currently navigating a period of uncertainty, with rising mortgage rates and declining sales creating a challenging environment for both buyers and sellers. As economic factors continue to evolve, stakeholders must remain vigilant and adaptable to the changing landscape. While the current conditions may seem daunting, they also present opportunities for those willing to engage with the market strategically. As the housing market seeks to find its footing, the next few months will be crucial in determining its trajectory.